
Why America Has Thousands of Banks
The US has more than 4,000 banks and nearly as many credit unions, far more than any other country. That competition is exactly why bank bonuses exist.
Why Does America Have Thousands of Banks?
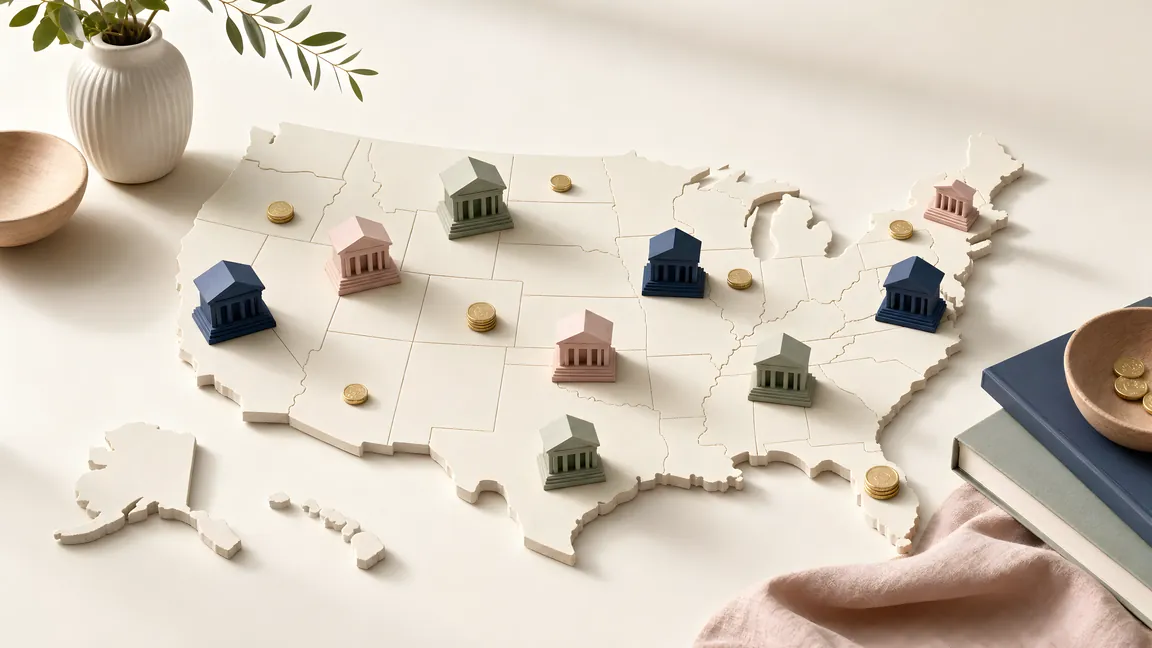
The United States has 4,278 FDIC-insured banks as of the FDIC's first-quarter 2026 data, plus about 4,250 federally insured credit unions, spread across tens of thousands of branches. No other country is close; most developed economies make do with a few hundred banks, and everyday banking concentrates into five or ten national brands.
That fragmentation is a quirk of American history. It also happens to be why your checking account can earn anything at all: thousands of institutions competing for deposits is what funds signup bonuses, high-yield accounts, and rewards checking.
Key takeaways
- 1
For most of the 20th century, U.S. law confined banks to a single state and sometimes a single building, so nearly every town grew its own bank.
- 2
Interstate banking only became legal in 1994, meaning consolidation has had barely three decades to run; the count has already fallen from over 14,000 banks in the 1980s to about 4,300 today.
- 3
Banks holding more than 10 percent of national deposits are generally barred from growing by acquisition, which caps how big the biggest can get.
- 4
Thousands of competing institutions means thousands of independent promotions, rate decisions, and bonus budgets running at once.
A country of one-town banks
Through most of American history, lawmakers who distrusted concentrated financial power wrote the banking rules. Many states enforced unit banking, meaning a bank could operate exactly one office. Federal law reinforced state lines for decades, so even successful banks could not follow their customers across a border. If a town wanted banking, the town needed its own bank, and thousands of towns built one.
The walls came down slowly: states loosened branching rules through the 1980s, and the Riegle-Neal Act allowed true interstate banking in 1994. Consolidation started the moment those walls fell. There were more than 14,000 banks in the mid-1980s; there are 4,278 as of the FDIC's first-quarter 2026 count. But mergers take time, and thirty years is not enough to erase a century of one-town banks.
One more brake remains: federal law bars any bank holding 10 percent or more of national deposits from growing through further acquisitions. The biggest names bump against that ceiling, which is part of why thousands of small institutions still have room to live underneath them.
Independent bank rates and bonus budgets
In a five-bank country, the banks compete gently and you take the rate they hand you. In a four-thousand-bank country, some bank is always hungry for deposits: a credit union raising its rewards checking rate, a regional bank running a $300 bonus to enter a new city, an online bank buying market share with a 4 percent savings rate.
Each of those institutions sets its own rates, its own bonus budget, and its own approval rules. The best offer in the country at any moment is rarely from the same institution two years running, and it is almost never from the biggest brand you know.
Related articles
Why bonuses exist, and where the small institutions shine.
Why Do Banks Pay You to Open a Checking Account?
Why banks pay $200 to $400 for new checking customers while paying almost no interest on checking deposits.
Cash Back Debit Cards in 2026: The Law That Decides Who Can Offer Them
The Durbin amendment capped debit-card interchange at large banks while exempting small institutions, creating different funding for debit rewards.
How Small Banks and Credit Unions Out-Pay the Megabanks
Small banks and credit unions compete for deposits with rates and bonuses that often exceed megabank offers.